The two strategies
Both methods pay every minimum, every month, and throw all extra money at one target debt. They differ only in how the target is chosen:
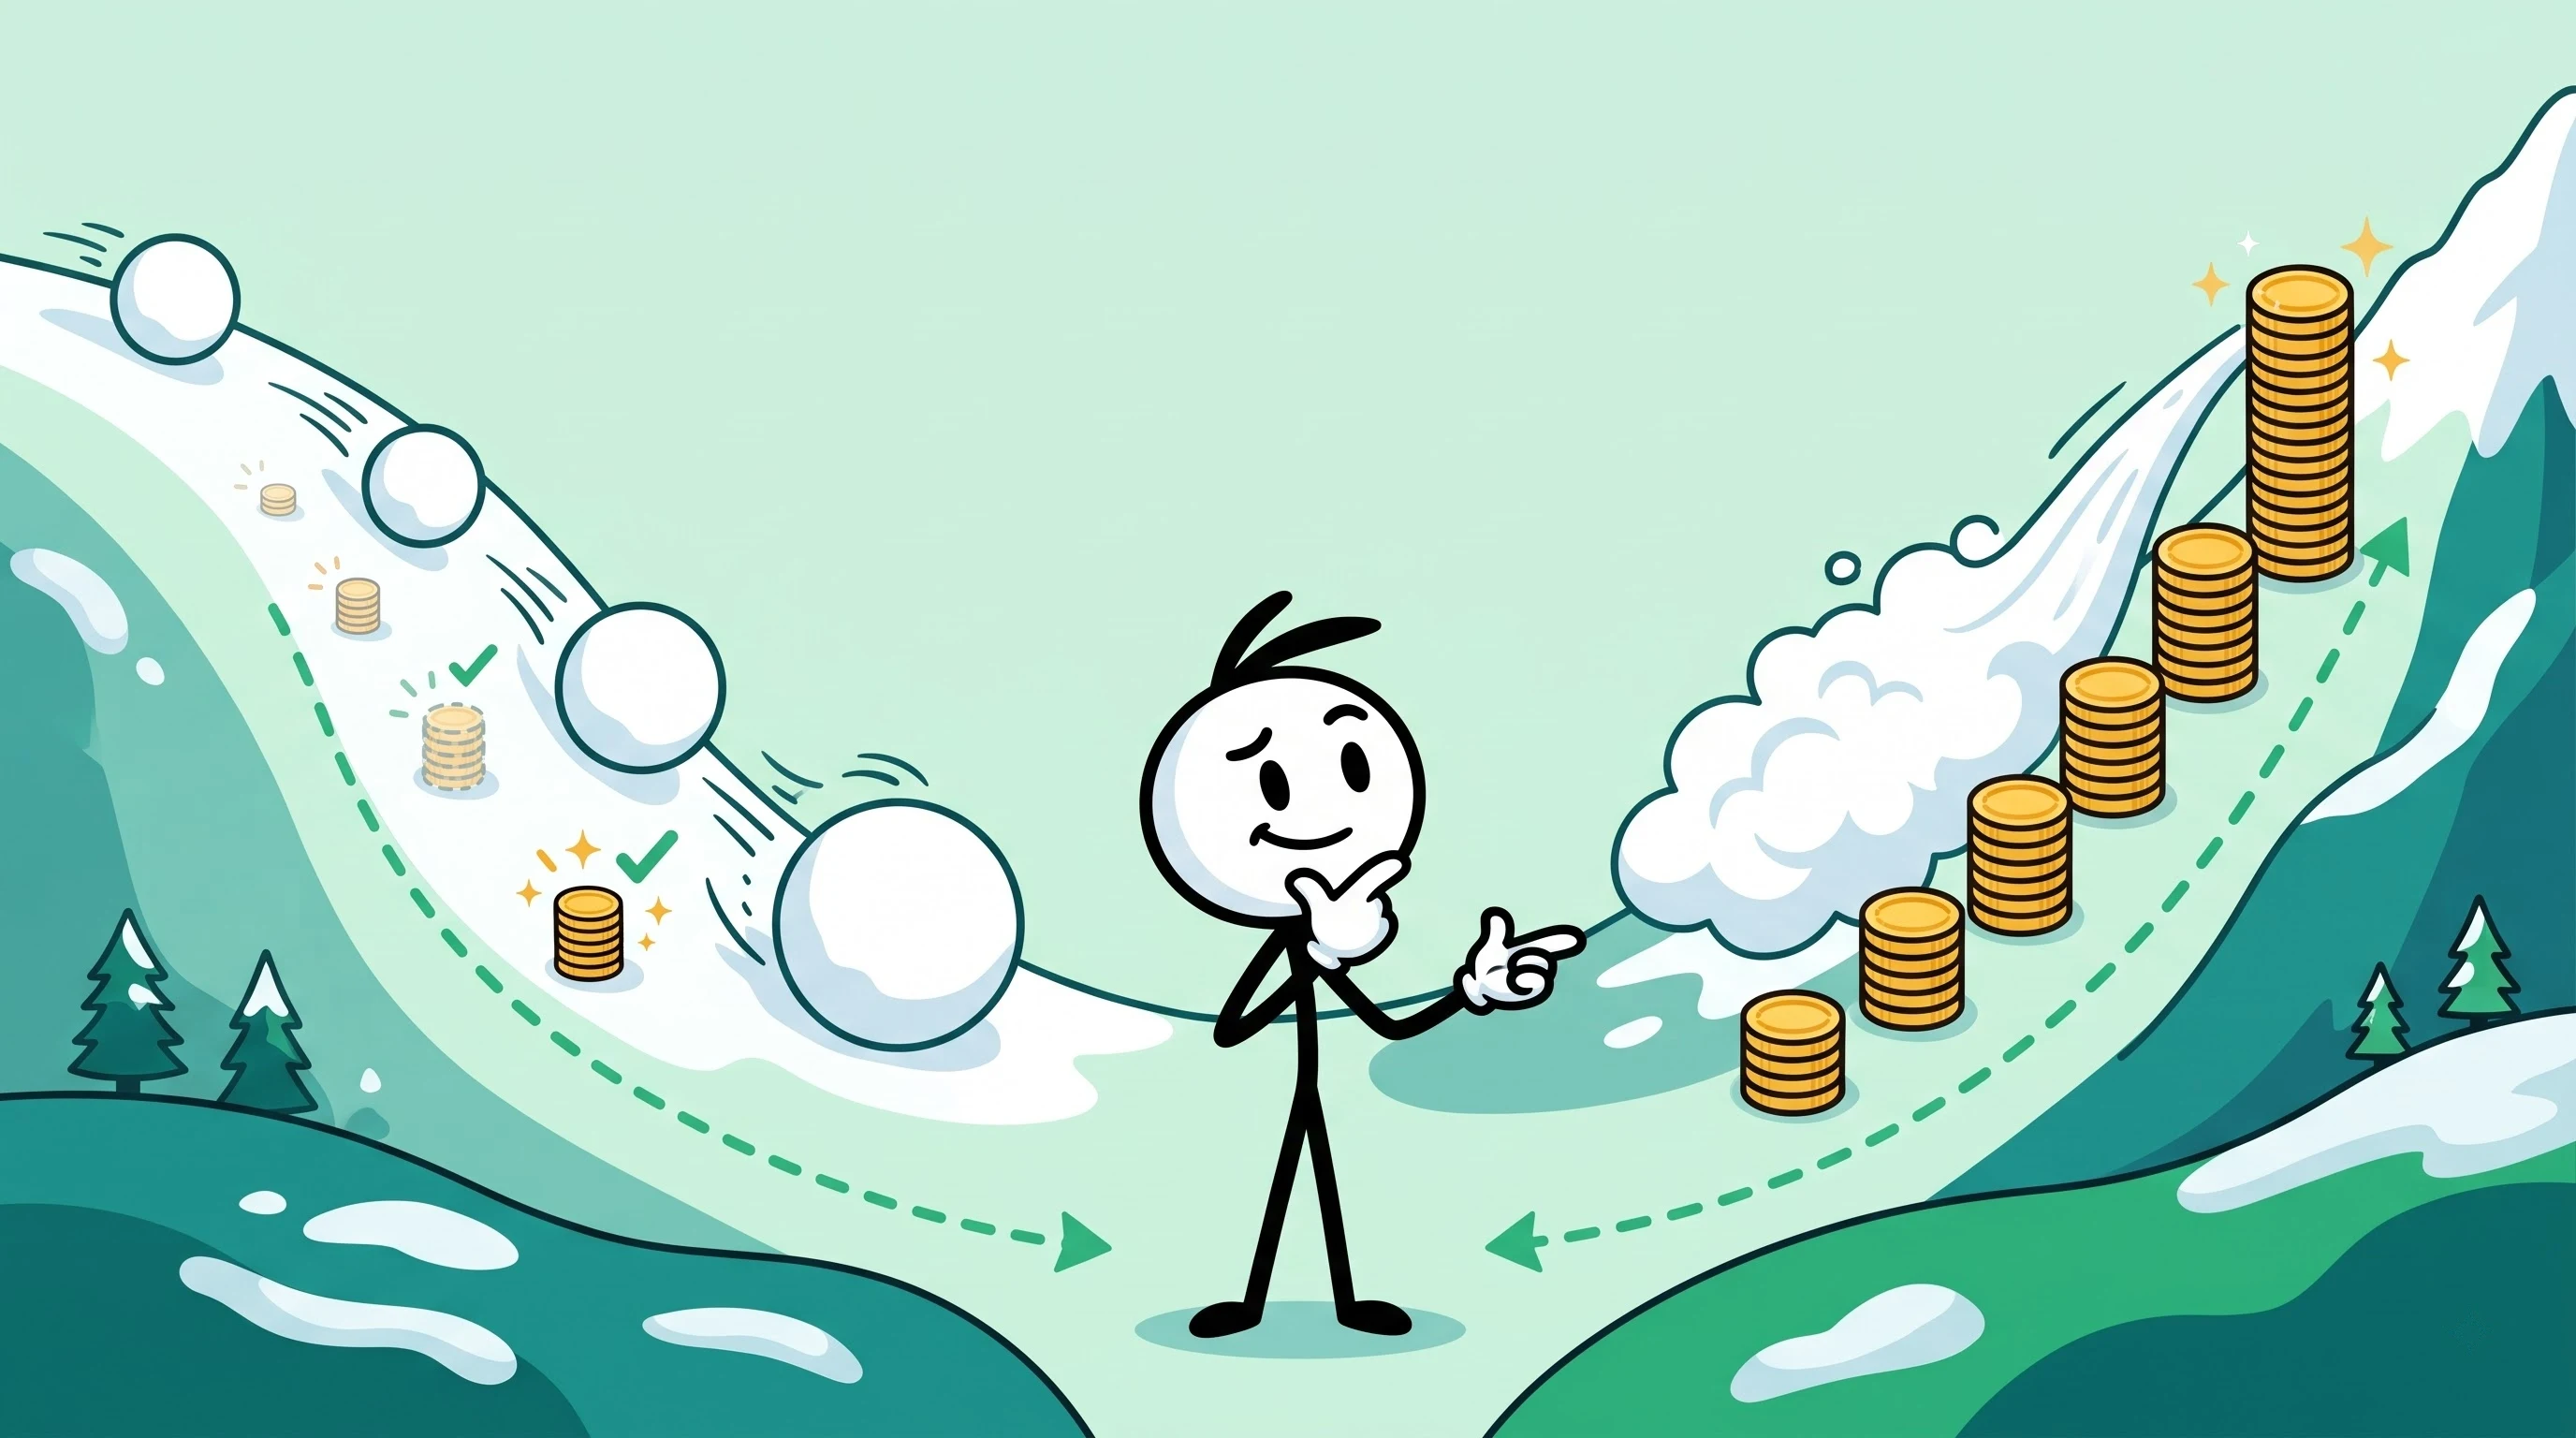
- Snowball: attack the smallest balance first. Debts vanish fastest, which keeps motivation alive.
- Avalanche: attack the highest interest rate first. Expensive debt dies first, which usually costs less overall.
When a target clears, its whole payment — minimum plus the extra — rolls into the next target. That rolling payment is the "snowball" both methods share.
Same debts, two outcomes
Assumptions: a $2,500 store card at 10% ($70 minimum) plus a$9,000 credit card at 21% ($220 minimum), with$150/month extra, fixed rates, no fees:
| Method | Debt-free in | Total interest | First cleared |
|---|---|---|---|
| Snowball | 41 months | $4,198.90 | Store card, month 12 |
| Avalanche | 36 months | $3,285.17 | Credit card, month 32 |
Avalanche wins here by 5 months and $913.73 — real money, but smaller than the internet's holy wars suggest. And snowball delivers a fully cleared debt in year one. Run your own numbers in the debt payoff calculator, which simulates both side by side.
How to choose
- Pick avalanche if you want the mathematically cheapest plan and trust yourself to stick with it through slow early months.
- Pick snowball if past plans died quietly — early wins are a feature, not a consolation prize.
- Either beats minimums-only by years. The extra payment matters more than the method.
Lender math may differ on fees and timing, and this is general education, not advice — see the disclaimer.
Quick answers
Should I save while in debt? Keep a small starter buffer, then aim everything spare at high-rate debt — its guaranteed "return" beats most investments.
What if minimums don't cover the interest? Balances grow forever; no strategy works until payments exceed monthly interest. The calculator says so plainly instead of inventing a payoff date.
Can I switch methods halfway? Yes — re-run the numbers when life changes. A plan you update beats a perfect plan you abandon.